

JOHCM UK Dynamic Strategy
Size
GBP 496.74m
“There is nothing so stable as change”
Bob Dylan
Change is at the heart of the UK Dynamic investment process. Change in management, change in capital allocation, change in focus and, if successfully applied, a change in returns and the share price. Change is usually only necessary when there is something that needs fixing. UK Dynamic’s approach to investing, fortunately, is not in that camp. It is a proven, scalable and replicable process and one the new team know well. It has delivered strong, idiosyncratic returns in a defined and consistent manner. We aim to keep it this way. So, whilst the makeup of the team itself has changed, the process will not. Steady evolution, disciplined and patient but active management is the order of the day. Change can indeed be stable.
Strategy Update
The Fund delivered 4.44% versus 3.43% for the index, a solid result and a reasonably pleasing one given it follows on from the strong finish to 2023. Newsflow across the portfolio has generally been very encouraging and, at this early stage, more stocks look like putting their shoulder to the wheel than the narrower cohort of last year.
The rates euphoria of 2023 has been replaced by a more pragmatic, scaled back view of when reductions might land, an opinion that looks justified by the mixed economic data. Other trends though have continued where they left off, with the tech heavy US continuing to power ahead, underpinned by an avalanche of AI driven spend, particularly in data centre and semiconductor capex, as well as a significant pick-up in biotech M&A. Europe has been sprightly and Japan, the new global allocators favourite, continues unabated. The UK market continues to languish at the rear.
At first blush then this might suggest nothing is changing, the world’s favourite underweight justifying its tarnished reputation, but the picture beneath the surface reveals a different picture. Volumes in the UK have been noticeably picking up. Investors are starting to take notice of 15 months of sterling stability and imminent political clarity too, particularly when elections elsewhere have less certain outcomes. Consumer and business confidence is on the rise, and we have seen a pleasingly robust results season, allied to a clear willingness by companies to pro-actively set down capital to invest. Real disposable incomes are growing at a nice clip, house prices have stabilised, and the post COVID de-stocking cycle is largely complete. Taken together this is quite a way from the sluggish, near recessionary backdrop perception that dominates the domestic narrative. In short, the fundamentals are clearly improving and yet the UK market is eye-openingly cheap. This is not new information, but markets have a highly frustrating habit of taking a lot longer than you think and then getting there a lot quicker than you think. Time will tell if that happens, but the anecdotal evidence is mounting up.
UK corporates though are not sitting on their hands and waiting for change to come to them, they are proactively doing something about it. The valuation disconnect that has persisted so long is
finally being confronted. Companies are re-focusing, improving returns, investing confidently, all whilst hoovering up their equity at distressed multiples. Witness for example, Barclays, which will return approximately 50% of its market capitalisation over the next three years in buybacks or distributions. When the market is valuing you at 0.4X tangible book and you are making near double digit return on equity this is undeniably the route to go down and it has finally injected life into the moribund share price. BP too is stepping up its own buyback to a cadence of an incredible $3bn per quarter, a clear capital allocation positive when you are on a ~15% free cashflow yield, and yet it still has plenty left over to invest in growth optionality like its market leading electric vehicle (EV) charging network.
Another playbook that is seeing a welcome pick up in frequency, and is a key building block in successful business transformations, is the sale of non-core subsidiaries at meaningful premiums to their implied value. The positive impact of disposals on shareholder returns can be magnified when the capital released is recycled into the higher returning base business or, as per above examples, used to retire equity that is trading materially below intrinsic value. UK Dynamic saw a couple of key examples of the latter over the quarter including ITV which sold Britbox International and Johnson Matthey which sold its medical device component business, both for substantially more than market expectations. We are encouraging both WPP (Kantar) and Elementis (Talc) to go down a similar path.
But even all of this has been overshadowed by the thundering cavalry of trade buyers coming over the hill. Last year was a very busy period for UK incoming M&A, but 61% of these transactions were by financial buyers. This year, while these buyers have not gone away, they have been joined by the trade buyers. This is a very important development. Trade buyers typically need inordinate confidence in the outlook before they move, so their very actions are an unambiguous positive indicator. These buyers can also extract synergies and synergies can justify higher premiums. That the UK has rapidly become a feasting ground for such transactions is no coincidence - it is a direct consequence of high-quality businesses trading at the wrong price. At the time of writing there have been 12 such transactions in just the first quarter alone with delivered premiums the highest since 2018. Given the nature of the UK Dynamic assets we would expect the Fund to be a disproportionate beneficiary of such a backdrop, a view not without foundation given the announced but failed approach by Ageas for Direct Line and further rumours of approaches for Elementis.
Examples of UK corporate activity in 2024
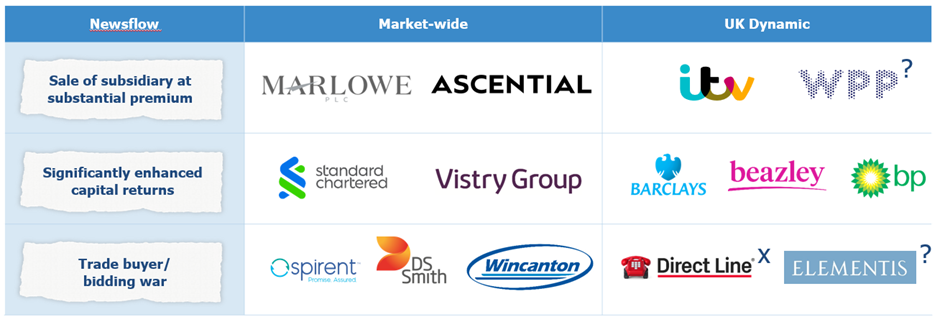
Source: Bloomberg
Performance – positive contributors
It was a strong earnings season for the Fund. Good results and higher than anticipated capital returns drove healthy appreciation at Beazley. Pleasingly the growth was high quality, balanced across the cyber, property and specialist books, with operating efficiency evident in the low combined operating ratio and the robust financials (with Solvency II comfortably in excess of 200%). This suggests the company’s announcement of a £200m buyback is prudent. Despite the share price move the stock still only trades at 1.2x book for a high teen return on equity business with enviable positions in niche markets. The valuation remains on a noticeable discount to peers and its own long-term average. The Fund has increased its absolute position size.
Rolls Royce, the best performing stock in Europe last year, has continued in fine fettle into 2024. Results were excellent across the board with strong cashflow a notable highlight and resulting in an investment grade credit rating earlier than expected. The cultural turnaround and refocusing engineered by Warren East, has been sharpened and accelerated by CEO Tufan Erginbilgic, with a notably tight commercial focus. Allied to a favourable recovery in its end markets, the business has very strong momentum, engendering confidence that forecasts can continue to be exceeded. We believe that a £4bn cashflow target is now a credible aspiration. Furthermore, we remain excited by the growth optionality around key areas of power systems such as data centres and micro grids, as well as huge, longer-term opportunities like SMRs (small module nuclear reactors) and the revolutionary Ultrafan engine, which provides the gateway for an ultimate return to the fast-growing narrowbody market.
In the Life assurance space conditions have become markedly more favourable in recent months and Aviva, post its refocusing, is well placed to benefit. Under CEO Amanda Blanc the company has exited six disparate international markets to focus back on the core and reinvest in organic opportunities. The results clearly demonstrate this is starting to have an impact, with its leading proposition in workplace pension and strong bulk annuities presence both offering a multi-year growth runway. This, combined with an improving backdrop in general insurance have led the Group to upgrade its medium term guidance, but even then we feel the £2bn operating profit objective looks on the conservative side.
Convatec numbers were impressive. The bedrock ethos of investment led product innovation, so clearly laid out (and delivered) by Karim Bittar is starting to gestate through the P&L. Organic growth has accelerated in all of the key divisions and the portfolio vitality (defined by the company as the percentage contribution coming from new products) continues to improve. This is a long cycle asset so the impact of this should be enduring. The market is starting to recognise this and has narrowed the valuation gap with key international peers. In recognition of this, whilst we retain our core confidence, the Fund has reduced its position.
Performance – negative contributors
Dowlais has noticeably failed to participate in the rally of global auto peers, driven principally by extended technical pressure post the Melrose demerger, higher interest costs and a non-cash impairment at Powder Metallurgy. This is despite good operational execution, a moderation of EV headwinds, margin expansion, a share buyback and multiple director share purchases. The pro forma balance sheet position, however, has warranted some attention given pension contributions, provisions and leases. Whilst no single issue is unsurmountable, the cumulative impact on an operationally geared business means we will tread forward with caution and with a disciplined absolute weight allocation.
Moneysupermarket underperformed over the period driven principally by the delay of energy switching revenues into 2025 and insurance premium deflation meeting a tough comparative from last year. This has pushed out some of the more optimistic forecasts in the market and put the brake on the multiple after its strong run last year. Encouragingly though the data integration project, 18 months in the making, is now complete, releasing critical coding and engineering resource to focus on revenue generating activities. As a result, we expect the cadence of new releases and product innovation to accelerate, building on the encouraging momentum with membership-based customer propositions.
There was further disappointment at PZ Cussons over the quarter as additional Naira devaluation extended the balance sheet mismatch of its gross and net cash balances whilst also limiting the company’s execution flexibility. We had proactively further reduced the position size prior to the bulk of this move, which helped limit the damage, and are actively engaging with the management around options to put themselves in greater control of their own destiny.
That the housing market has been weak for a while and key building materials have seen some relative deflation is not news but even in this context the Travis Perkins numbers were still a disappointment. The new finance director is a welcome addition and his decisive action on curtailing ever expanding losses in Toolstation Europe is long overdue. Subsequent news that the CEO will be stepping down was the logical next step and we are encouraged by the Board’s actions as our concerns over urgency had been growing. We had been vocal in communicating our disappointment over the speed and scale of cost savings and footprint reductions. We still believe there is much more that can be done here. This is a market leading asset at a cyclical trough and so this is not time to abandon ship. Instead, we intend to engage and work alongside the Board to unlock the equity value upside that resides here.
Portfolio Changes
Three new ideas have been introduced to UK Dynamic in 2024 funded through exiting or reducing existing positions where we believed margins of safety were beginning to look stretched. These changes have also resulted in improved free cash flow and balance sheet metrics at the portfolio-level.
The Fund exited its position in Zegona Communications. The geared balance sheet left us unconvinced of the company’s ability to pay a dividend in the next fiscal year. The dividend requirement remains a core discipline of the UK Dynamic investment process. The proceeds were used to initiate a new position in the global fintech, IG Group, which has recently seen new CEO, Breon Corcoran, join. Breon was the CEO that transformed and merged Betfair, a turnaround that proved to be a very profitable investment for this strategy. The investment case for IG Group had already begun to look compelling with a recent developments including a reduction in regulatory capital requirements, a strong net cash balance sheet, emerging US and Japanese growth options, five additional growth incubators and the potential for operational gearing as underlying headcount is reduced.
The Fund also more than halved its position in Vodafone. Over the last two years UK Dynamic has been actively engaged in pushing for a simplification of the entity structure to attempt to unlock shareholder value. Management have now completed many of these actions, including the sale of operations in Spain and Italy and a potential combination with Three in the UK. However, although these disposals have resulted in a simpler business, they have also diluted free cash flow in the medium term. Financial leverage has not been sufficiently reduced by the disposal proceeds resulting in the need to halve the ongoing dividend. While this was the correct action, in our opinion, it now puts the shares on a mid-single digit dividend yield which is in-line with the sector.
We believe there to be a much larger margin of safety and attractive equity story emerging at BT Group where the Fund has initiated a new position. BT Group has been ‘building like fury’ to roll fiber out across the UK under its Openreach brand. The Group is currently in its peak year of capital expenditure which has put pressure on earnings and cashflows in the short-term but also built the foundations for a potential trebling in free cash flows to ~£3bn by the end of the decade. Our analysis suggests Openreach is significantly undervalued despite delivering over 60% EBITDA margins and potential mid-teen returns on capital employed.
Finally, the Fund retains a core position in 3i but the overall allocation has been reduced from ~6% to ~4%. The capital has been allocated to Associated British Foods - a £18bn FTSE 100 conglomerate focused on Grocery, Retail and Ingredients. Within this conglomerate, there are several global growth brands, the most interesting of which is Primark, the value for money clothing and household goods retailer which is now a proven roll-out story in multiple geographies. At the prevailing share price, we calculate the implied valuation for Primark as ~7X EV/EBITDA which represents a 60%+ discount to the Action valuation of ~18.5X EBITDA. As a reminder, Action now represents ~65% of 3i’s NAV up from 4% in 2012, and over half of the value increase has been due to multiple expansion. Going forward it is unlikely multiple expansion will be a further driver of value thereby the investment case relies on the sustainability of growth. Compared to Action, Primark delivers lower growth (24% vs 38%) but commands slightly higher margins (16% vs. 15%). In addition, there is management change at Primark, with new FD Eoin Tonge, ex CFO & Strategy officer at Marks & Spencer, joining just a year ago to replace the previous FD of 23-years. We are encouraged by the levels of improved disclosure and the tighter focus on capital allocation including the continuation of the share buyback and significant special dividend announced in November. We believe there is scope to go further and are engaging with management to push them to look at strategic options for the more volatile (though highly cash generative) Bread and Sugar divisions in order to refocus the capital into higher growth operations.
Outlook
It has been a strong earnings season for the Fund and for UK plc more broadly and there is increasing evidence that macro indicators are turning. The rate hike cycle of 2022 and 2023 has done little to slow the US economy with the most recent flash PMIs showing continued expansion and economic growth now broadening to include the UK and signs of a stabilisation in the Eurozone. Although inflation remains a lurking concern, the volatility in price changes and interest rate changes has reduced. In most cases, corporates have managed to repair balance sheets and now sit on close-to-record-high cash holdings.
This is an encouraging back-drop for UK Dynamic stocks. With most central banks signalling downward pressure on interest rates, corporate confidence in capital expenditure should rise. The Fund’s weightings towards pro-capital cycle sectors such as Financials, Industrials and Materials should mean it is a beneficiary of these conditions but so too should its bias towards owning well invested, strategically unique assets. Although inflation has slowed, its compound effect has been to significantly increase the replacement and/or replication cost of well invested assets. Given the discount of UK equity valuations relative to peers, and the increasingly supportive macro backdrop, it comes as no surprise to us to see UK plc experiencing elevated levels of corporate activity as global companies look to position themselves competitively for the next cycle. We believe the Fund’s portfolio of hidden quality assets are potentially attractive candidates.
UK Dynamic focuses on allocating capital to management teams that are successfully executing business transformations to unlock idiosyncratic drivers of shareholder returns. With the portfolio currently trading at an implied free cash flow yield of ~9% (ex. Financials) with a two-year forward compound earnings growth of ~15%, these changes appear to still be undiscovered by the market. Looking at our own forecasts, we believe the Fund should be able to generate dividend growth towards the top end of the previously guided 2-5% range despite delivering a handsome yield in 2023.
In combination, these factors give us the confidence that the Fund can continue to drive future and consistent outperformance. After all, there is nothing so stable as change.


As uncertainty rises and AI reshapes markets, where are opportunities emerging? Explore how a transformation-driven approach uncovers mispricing and long-term advantage in complex markets.
Fund Managers Vishal Bhatia and Tom Matthews discussed how increasingly “black and white” equity markets- where capital is concentrating in a narrow group of companies—are creating a broader opportunity set for active investors. They reviewed first‑quarter performance and highlighted business transformation opportunities that have the potential to unlock recurring shareholder value.
Explore key insights from the UK Dynamic Quarterly Update, covering portfolio positioning, shifting sentiment, and resilient stock selection amid uncertainty.
A review of 2025’s equity resilience and what shifting fundamentals, valuations, and politics mean for markets in 2026.
From our very first conversation to ongoing support, our teams of experts are here to answer your investment needs.