

JOHCM UK Dynamic Strategy
Size
GBP 496.74m
“Clarity is the bridge between confusion and understanding. In the midst of chaos, seek clarity.”
Anonymous
In the context of the UK’s very recent political history there is no denying it is quite a shift to be talking about clarity. But post the decisive majority delivered in the early July elections and a broad sweep across the state of nations elsewhere, it is not such a bold statement as it first appears. After having its political midlife crisis early and delivering Brexit as a byproduct, the UK has retreated to the safe refuge of the centre at precisely the same time others are splintering in all directions. Indeed, France has had to pull out all the stops to supress the far right, while Germany has a myriad of structural problems, the combination leaving a vacuum of leadership at the EU that it is increasingly seeing it succumb to the more hardened predilections of backseat drivers. In contrast, Latin America has gone completely the other way, embracing a noticeably hard left doctrine at the same time as Asia has the precarious and highly fluid Sino US influences to navigate. Even the US has a leadership crisis of its own, faced with an invidious choice between a freewheeling convicted felon or an incumbent demonstrating a precipitous decline in mental acuity. Set against all this, the UK really does look a haven of tranquillity.
More pertinently though, it will finally allow investors to look through the same set of facts through a more openminded lens, revealing positives that have been hiding in plain sight but obfuscated by a previously prevailing toxic narrative. In fact, the UK is in surprisingly good shape. There is near £300bn of excess domestic savings that remain unspent allied with surging real wages amongst those with the highest propensity to consume. Corporates are in similarly robust shape with strong balance sheets to deploy and a willingness to invest, demonstrated by business confidence touching an eight-year high. The UK has a world class education and academic infrastructure, a leading position in life sciences and is a clear number three in the world in technology alongside a thriving AI ecosystem. In other words, the UK is not just cheap, there is real potential for structural growth too. That’s why foreign direct investment has been picking up, headlined by a rising share of European projects and flagship names like Microsoft and Google, something that has not gone entirely unnoticed by the currency, which has been flirting with 18month highs on the major crosses.
UK consumer cashflows growing at double digits
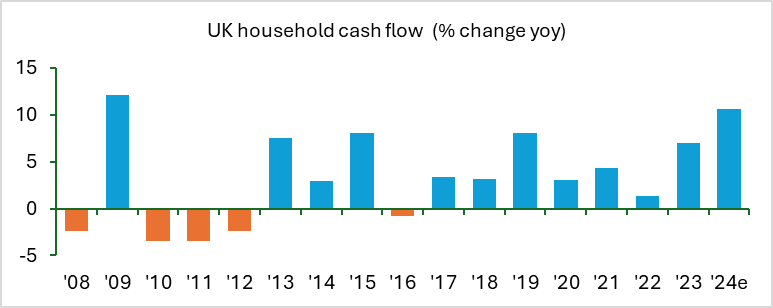
So, although it might be pushing it to say there is chaos elsewhere, it is certainly not pushing it to say there is a clearer and improving picture back home. Time will tell if the new political leadership can build on this, but in the short term the rally in UK domestic assets with ITV, Crest Nicholson, Tesco and Centrica among them, looks justified and the opportunity set looks compelling. Such a backdrop should suit JOHCM UK Dynamic’s approach well. At the portfolio company level, it can help unlock hidden quality and release value. It can allow superior capital allocators to flourish. And it can do so from a fabulously cheap, well diversified and increasingly attractive palette of assets.
Performance – positive contributors
BT’s results were in line with expectations but future cashflow expectations were significantly upgraded, underpinning management’s increased confidence in the high-speed fibre rollout and next generation network potential. This has been apparent on our recent engagements with management, but on which the market has been sceptical. Despite a punchy 17% move on the day, the shares are still dramatically under-reflecting the significance of this development and how it will cascade very powerfully down to the equity. Indeed, in an environment where at the margin they are seeing less competition not more, and with the impact of productivity enhancements still to flow through, the shares still trade on a monster free cash flow yield as the capex rolls off and the multi-year transformation starts to truly bear fruit. Our confidence has increased as a result and our position size has done likewise.
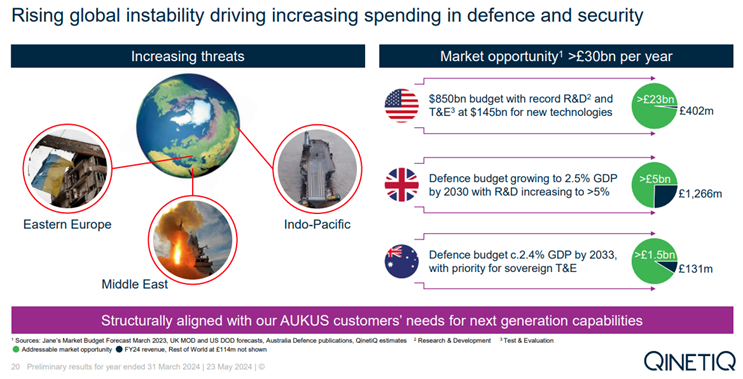
The unfortunate re-emergence of geopolitical turmoil has necessitated a rapid reassessment of nations defence and security infrastructure. This, combined with the striking learnings from the battlefield of recent conflicts, means we have already entered a potentially decades long global re-armament cycle. Whilst this spells bad news for government coffers, it is a meaningful positive for QinetiQ who have the skills and experience in the next generation technology areas that can hopefully make the world a slightly safer place. The company demonstrated its strong strategic positioning by unveiling a better than expected outlook and a substantial pipeline for its high technology service suite. After an ill-timed acquisition, which caused unnecessary distraction a couple of years ago, management has refocused its capital discipline, which in turn is creating greater optionality for investment in growth and further shareholder returns.
Another company that got waylaid by misplaced ambition, NCC, is on a similar path to redemption. The business is being reinvigorated by a strong new management team returning it to its core competences, thereby placing it firmly in UK Dynamic territory. Like QinetiQ, it has a skill set well equipped for the modern world, in this case being the leading independent cyber security consultancy in the world. As well as a robust trading update, well received mini capital markets day on its Escode and managed security propositions respectively, showcased its enviable armoury of offerings to improve corporate resilience and defences in a world of ever escalating threats. AI is only going to push that in one direction; whether we like it or not companies need to be prepared and NCC is increasingly becoming their partner of choice to do so.
The elevated M&A environment for UK assets which has prevailed for some time, and documented here last quarter, shows precious few signs of slowing down in fact, quite the opposite with 17 transactions, totalling £43bn, in the FTSE 350 as the time of writing. This compares just 2 at this stage last year (when transactions were weighted more to the smaller end). Pleasingly this has not passed the portfolio by, as another incoming approach surfaced over the period with Crest Nicholson attracting the interest of industry peer Bellway. Given the enviable land bank and significant discount to book value, it is no surprise that this asset has been coveted from those within the tent, especially as prior combinations in the sector have delivered tangible, proven synergies. Bellway’s approach has tempted others into the fray, with private peer Avant also throwing its hat into the ring in recent days. This should provide the springboard to unlock the nascent value that has always lurked within Crest (but thus far proved tantalising elusive to extract); we remain hopeful of securing a price that reflects its true potential.
Meanwhile Anglo American was also the recipient of a short-lived approach from BHP. The management, correctly in our opinion, rebuffed this proposal given that it presented undue complexity alongside less than full and fair value for its world class copper assets. The proposal has highlighted the attractions, but the company now needs to get its head down and execute on its simplification plan to deliver optimum returns for shareholders. Indeed, this may well be the end of the ‘old’ Anglo as we know it, with a tighter more focused capital allocator emerging on the other side.
Performance – negative contributors
The Healthcare sector numbers for the quarter do not make pretty reading. Non-ownership of Astra Zeneca, the biggest stock in the UK but also one largely shorn of the characteristics which make a typical UK Dynamic stock, was the biggest detractor over the period, clocking up over 80bps of relative performance drag.
Sadly, our more proactive industry pick, GSK far from offsetting this impact, merely added to it as it surrendered gains from earlier in the year. Our view has been that the Zantac litigation and associated liabilities were already more than discounted in the price, masking an improving R&D productivity story and a broadening pipeline of attractive therapeutic assets. Given the Delaware court reversal in the key Daubert case on this issue, and the renewed uncertainty this has caused, it is clear that at least in the short term, this view has proven to be misplaced. Despite strong Q1 results lending clear credence to the core fundamental story, and whilst an appeal has already begun and previous precedents lean heavily in favour of the equity at this juncture, we are not naïve enough to believe recovery can happen in the absence of this being resolved. The shares are clearly very cheap, and the underlying progress tangible, but we will manage the position size proactively in this period.
Completing this decidedly unholy trinity was Convatec. The company gave back some of its strong performance from earlier in the year on a new US regulatory development which may impact the coverage and pricing determinations for specialist foot and leg ulcers, as well as some emerging risks over reimbursement in the catheter segment. Investors may recall we had pre-emptively significantly reduced the position size here, primarily on valuation grounds and that helped moderate the impact. Meanwhile, underlying operating performance continues to be strong, with accomplished CEO Karim Bitar’s strategy of prioritizing R&D and innovation starting to bear fruit and giving credible reasons to be optimistic on long term growth.
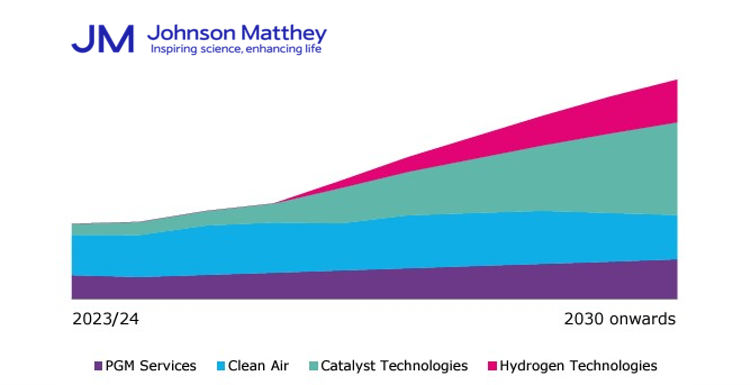
Away from healthcare, a more positive negative (if such a phrase is indeed permissible in polite society) was observed at Johnson Matthey. Whilst the stock saw short term downgrades from the continued weakness in PGM services, the underlying results themselves were of a pleasingly good quality with tangible progress on the meaningful drivers of long-term value creation. The company raised its long-term Clean Air division cashflow forecasts once more, and has sensibly reduced capital allocated to long-tail projects with uncertain payoffs while awaiting a more supportive regulatory regime. It has redirected those funds towards Catalyst Technologies, where it has an exciting array of solutions and a clear competitive advantage. Even the slightly beleaguered PGM division has light at the end of the tunnel, with a newly announced refinery set to unlock very substantial working capital benefits, repositioning it towards more complex product and areas of stricter recycling regulations that can unlock higher margins. In short, we believe the weakness to be misplaced and have added to the Funds position to take advantage.
Building underlying operating growth at Johnson Matthey
Outlook
The UK is very much ‘open for business’, indeed we are arguably at the start of a new capital cycle. Continually elevated corporate activity is one clear proof point of this but more recent additions to the mix are arguably even more significant. Notably, capital raisings have re-appeared with a vengeance with National Grid’s substantial rights issue, the biggest in the market since 2008, funding its monster £32bn capex upgrade plan for the nation’s electricity backbone. We don’t own National Grid (it has 5x net debt:ebitda after all) but we do own stocks that will benefit directly or indirectly from this investment. More significant perhaps is the signal it sends about the UK as a place to invest and its’ equity markets reemerging as a credible fundraising option for growth capital. Meanwhile on a smaller scale, but no less interesting, was a similarly pro-active deal from Great Portland Estates to fund asset purchases at what they believe (and arguably explicitly called) the bottom of the cycle. This stock is also not held in the portfolio, but, if true, certainly portends well for Land Securities and Shaftesbury Capital.
Other signals of confidence are emerging too. There is tentative early evidence of a broadening out, with the first glimmers of performance emerging in small and mid-cap assets for a considerable period; alongside this volumes and block placings are picking up, the IPO market is beginning to stir, and international enquiries are continuing to build. Meanwhile the Banks are showing a clear willingness to lend, with loan books forecast to be in consistent growth for the foreseeable forecast period. Again, this is a marked departure from recent history, and it is worth noting that the last time the banking sector was in consistent loan book growth they traded at 1-1.5x tangible book value (and on NAV that was accreting) versus the 0.6-0.9x they typically reside at today (on a NAV that has been more pedestrian). Barclays, which trades at the lower end of this range, looks particularly attractive in this context.
It is not just that the banks are very cheap, it is what they can help unlock. Collectively, the above examples show the wheels of capital provision are starting to turn and access to growth capital for deserving businesses is starting to be unlocked. All else equal, this should naturally lead to a pick-up in productive investment, economic growth, productivity and prosperity. It is a tantalising prospect, but crucially one that UK equities are light years away from discounting. The opportunity set is a rich one and potentially very fertile for the portfolio positioning and process. But it is one that will need rigour and focus to take best advantage, something we very much intend to adhere to. Clarity, after all, might provide the bridge to better understanding, but it does not guarantee returns. There remains no substitute for a disciplined, consistently applied process.


As uncertainty rises and AI reshapes markets, where are opportunities emerging? Explore how a transformation-driven approach uncovers mispricing and long-term advantage in complex markets.
Fund Managers Vishal Bhatia and Tom Matthews discussed how increasingly “black and white” equity markets- where capital is concentrating in a narrow group of companies—are creating a broader opportunity set for active investors. They reviewed first‑quarter performance and highlighted business transformation opportunities that have the potential to unlock recurring shareholder value.
Explore key insights from the UK Dynamic Quarterly Update, covering portfolio positioning, shifting sentiment, and resilient stock selection amid uncertainty.
A review of 2025’s equity resilience and what shifting fundamentals, valuations, and politics mean for markets in 2026.
From our very first conversation to ongoing support, our teams of experts are here to answer your investment needs.